Reefer Breakdown Insurance
Temperature Records, Exclusions and Claims Preparation
A refrigerated shipment can lose value without a collision. Equipment failure, an incorrect setting or a temperature excursion can trigger a customer claim even when the truck reaches its destination on time. Reefer breakdown cargo insurance should therefore be reviewed against the freight, equipment and handling practices involved.
The coverage name alone does not establish that every spoiled load is insured. The actual endorsement may distinguish mechanical failure from driver error, inadequate maintenance or other causes. Review the details before accepting a temperature-sensitive shipment.

Separate freight protection from equipment repair
Cargo coverage may address covered loss or damage to transported goods. Physical damage or another equipment protection arrangement addresses a different interest in the truck, trailer or refrigeration unit. One should not be assumed to supply the other.
A failed cooling unit can create both a repair expense and a freight claim. Ask how each part would be evaluated under the proposed policies. The cause of failure and the wording can affect the answers.
Also review liability assumed under the transportation contract. The customer may demand compensation broader than the available insurance. A contract accepting every temperature-related claim does not automatically make all such claims covered.
Describe the commodities precisely
Fresh produce, frozen food and pharmaceuticals can have different handling requirements and values. Give the representative the actual commodity mix, maximum load values and any specialized requirements. A general statement that you haul refrigerated freight may not be enough.
Identify mixed loads and occasional higher-value shipments. Ask whether a special limit or restriction applies to any part of the load. The main cargo limit does not necessarily describe every applicable sublimit.
Review the customer’s written temperature instructions before pickup. Clarify conflicts among the rate confirmation, bill of lading and other instructions. Accurate operating records begin with a clear requirement.
Compare the covered causes of loss
Ask whether the endorsement responds to refrigeration equipment breakdown, temperature change, operator error or only defined events. Different forms and enhancements can treat these situations differently.
A hypothetical mechanical failure after documented maintenance is not necessarily evaluated the same way as an incorrect setpoint or a unit intentionally switched off. Do not assume the outcome from one scenario answers all the others.
Carrier marketing descriptions can help identify questions, but the issued form controls. If broader protection is offered, confirm eligibility and the actual endorsement rather than assuming it is automatically included in every policy.
Keep maintenance records accessible
Follow the equipment manufacturer’s maintenance requirements and the policy’s conditions. Retain service dates, work performed and reports of defects. A breakdown investigation may require information about the unit’s condition before the trip.
Drivers should know how to report an alarm or cooling problem promptly. Create a response process that includes dispatch and the appropriate service contact. Waiting until delivery can allow a manageable issue to become a larger loss.
Do not treat insurance as a replacement for safe equipment operation. A known defect deserves attention before accepting freight, and coverage should not be assumed simply because the business has paid a premium.
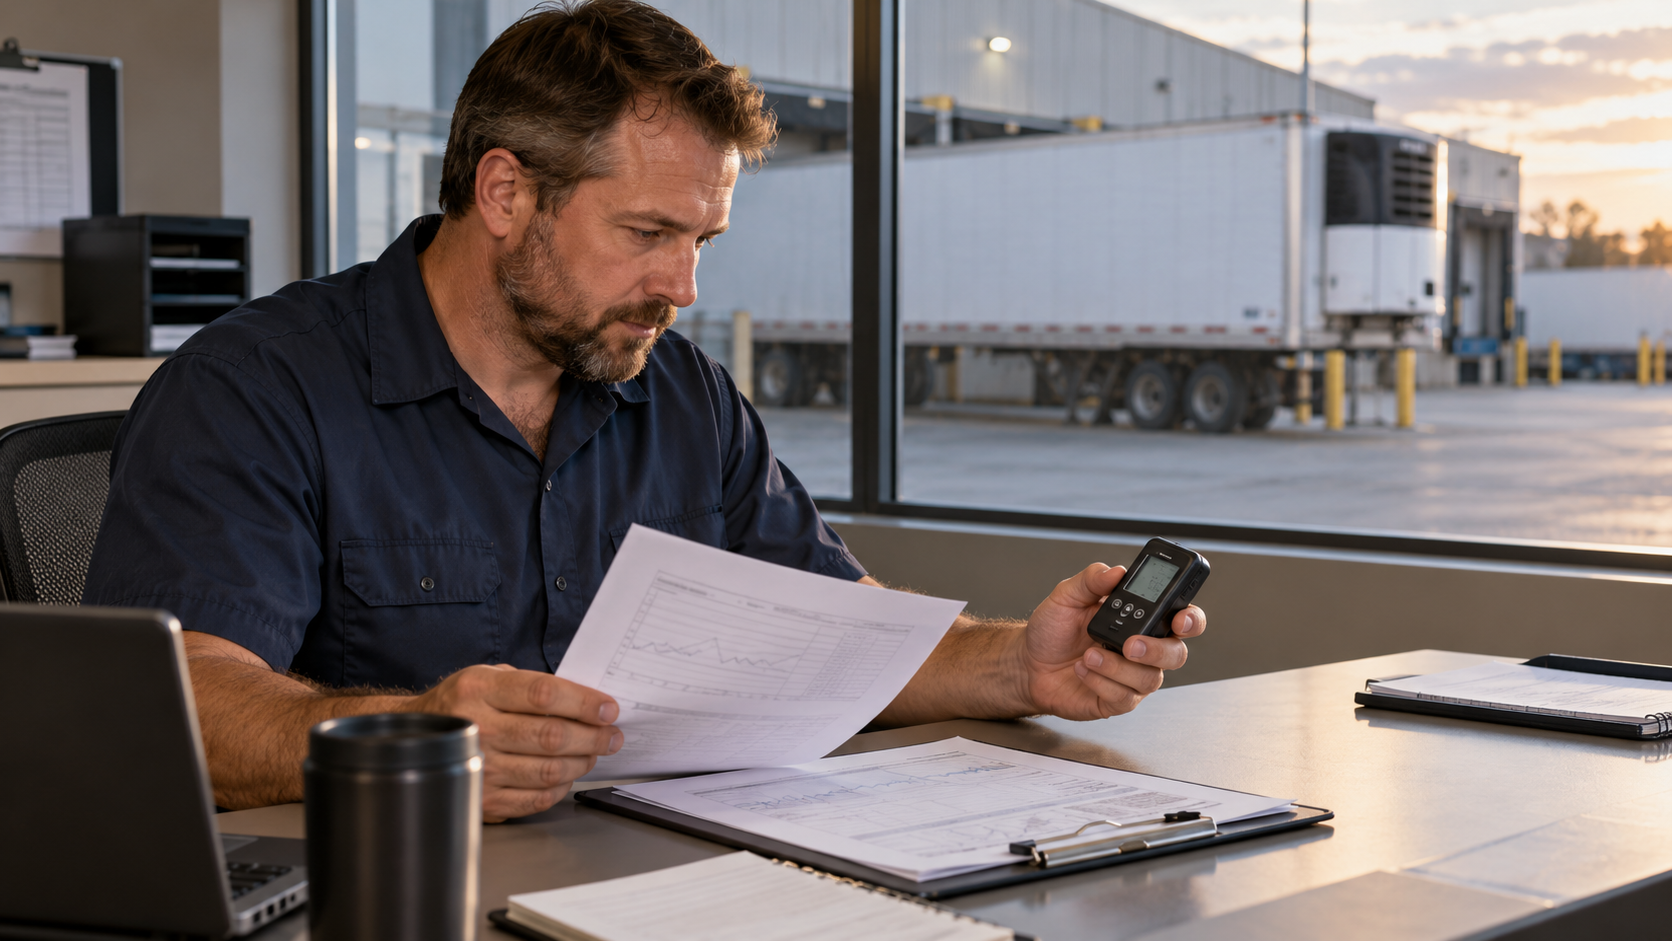
Record the shipment's temperature history
Document the prescribed temperature, pre-trip checks, pickup condition and relevant readings through the trip. Use the monitoring method appropriate to the freight and your procedures. Keep records in a form that can be retrieved after delivery.
Ask about requirements for continuous versus start-stop operation where applicable. Confirm who may authorize a change and how instructions should be recorded. A verbal message without a clear record can create uncertainty later.
Preserve seal information, delivery exceptions and communications with the shipper or broker. These facts can help establish the sequence of events. They support investigation but do not override an exclusion or prove liability by themselves.
Respond carefully to a rejected load
Prioritize safety and follow the insurer’s reporting instructions. Preserve temperature data, photographs, bills of lading and customer communications. Ask for written details about the rejection and the alleged condition of the freight.
Do not authorize disposal, salvage or a settlement without appropriate guidance. The insurer may need to inspect the goods or investigate alternatives. Follow any applicable safety and handling requirements while coordinating the response.
Document efforts to prevent further damage. Mitigation expenses and responsibilities should be discussed with the claim contact. Do not assume every expense incurred after rejection will be reimbursed.
Review limits and operating procedures together
Choose the cargo limit and deductible using credible load values and available reserves. Ask about expenses associated with disposal, cleanup or other handling after a covered loss. Availability and special limits vary.
Give RJS the equipment schedule, maintenance practices, commodities and contracts. Some RJS package options may include reefer-related protection, subject to carrier and policy terms. Confirm the option actually offered for your operation.
A useful review should leave dispatch and drivers knowing which loads fit, which records matter and when to request help. The best time to resolve a temperature-coverage question is before the freight is on the trailer.
The Answer
Q&A: Reefer Breakdown Insurance
Does ordinary cargo coverage insure every spoilage loss?
No. Review whether refrigeration breakdown or broader temperature protection is included and how the form treats the cause of loss. The cargo limit alone does not answer that question.
Is driver error covered?
It depends on the policy and endorsements. Incorrect settings, monitoring errors and mechanical breakdown can be treated differently. Ask the representative to explain the actual offered form.
Does reefer cargo insurance pay to repair the cooling unit?
Not automatically. Protection for damaged freight and protection for the equipment are separate questions. Review physical damage and any applicable equipment or breakdown options alongside cargo coverage.
Which records matter after a temperature claim?
Preserve instructions, readings, alarms, maintenance history, pickup and delivery records, photographs and communications. Follow claim instructions promptly and retain the original data rather than only a summary.
Can I dispose of rejected freight immediately?
Coordinate with the insurer and responsible parties before authorizing disposal, while following applicable safety requirements. Inspection, salvage and mitigation questions may need to be addressed first.
Get a free quote from RJS
Before accepting temperature-sensitive freight, ask RJS to review the available cargo and equipment options using your real shipment and maintenance details. Review your operation with RJS Truck Insurance and request a free quote at our truck insurance quote page. Coverage, eligibility and payment arrangements depend on the insurer, state and policy selected.
Get a Free, no-obligation quote today!
Fill out the form below to get the process started.